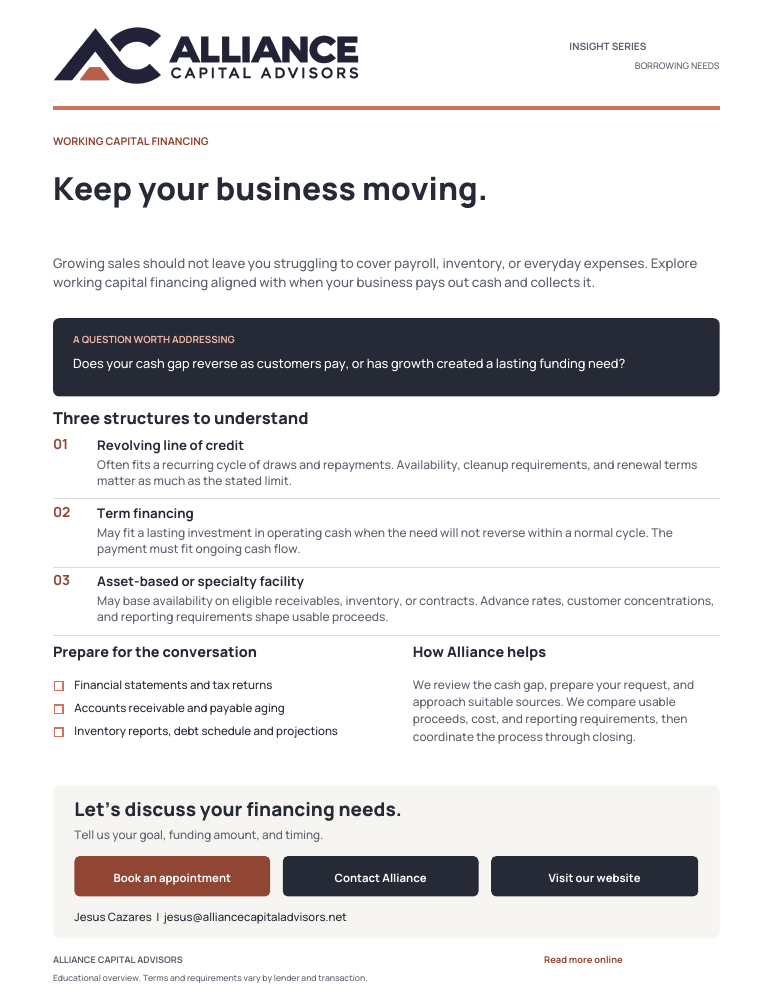
Growing sales should not leave you struggling to cover payroll, inventory, or everyday expenses. Explore working capital financing aligned with when your business pays out cash and collects it.
Explore this topic ↗GUIDES & CHECKLISTS
Commercial financing guides and checklists.
Prepare for lender questions with practical documents, transaction checklists and plain-English explanations of the measures behind financing decisions.
Financing flyers
Sixteen one-page guides covering borrowing needs, financing sources, and the steps from preparation to closing. Choose a topic to view or download its PDF.
Download all 16 flyers ZIP16 flyers · English PDFs
Borrowing Needs
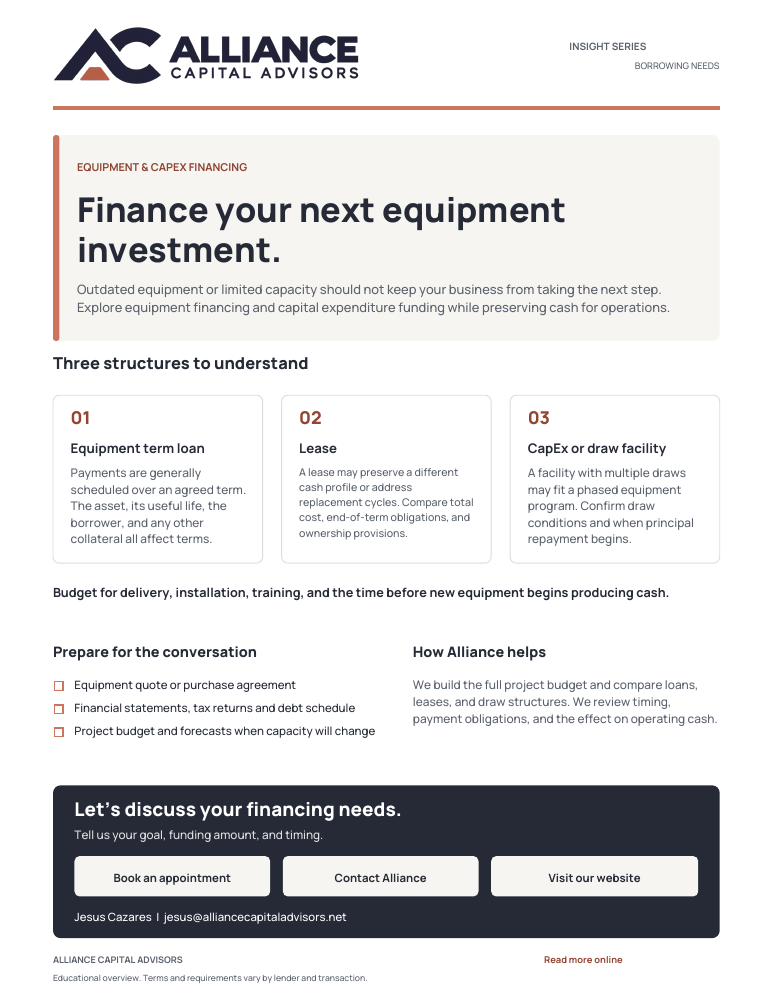
Outdated equipment or limited capacity should not keep your business from taking the next step. Explore equipment financing and capital expenditure funding while preserving cash for operations.
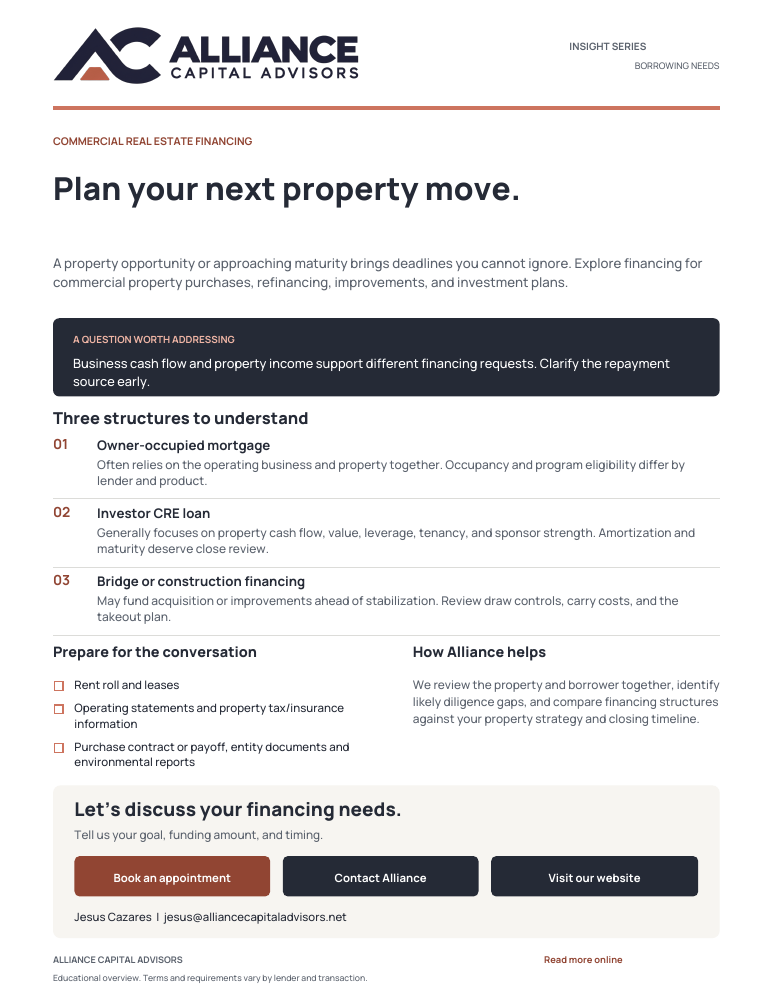
Explore this topic ↗A property opportunity or approaching maturity brings deadlines you cannot ignore. Explore financing for commercial property purchases, refinancing, improvements, and investment plans.
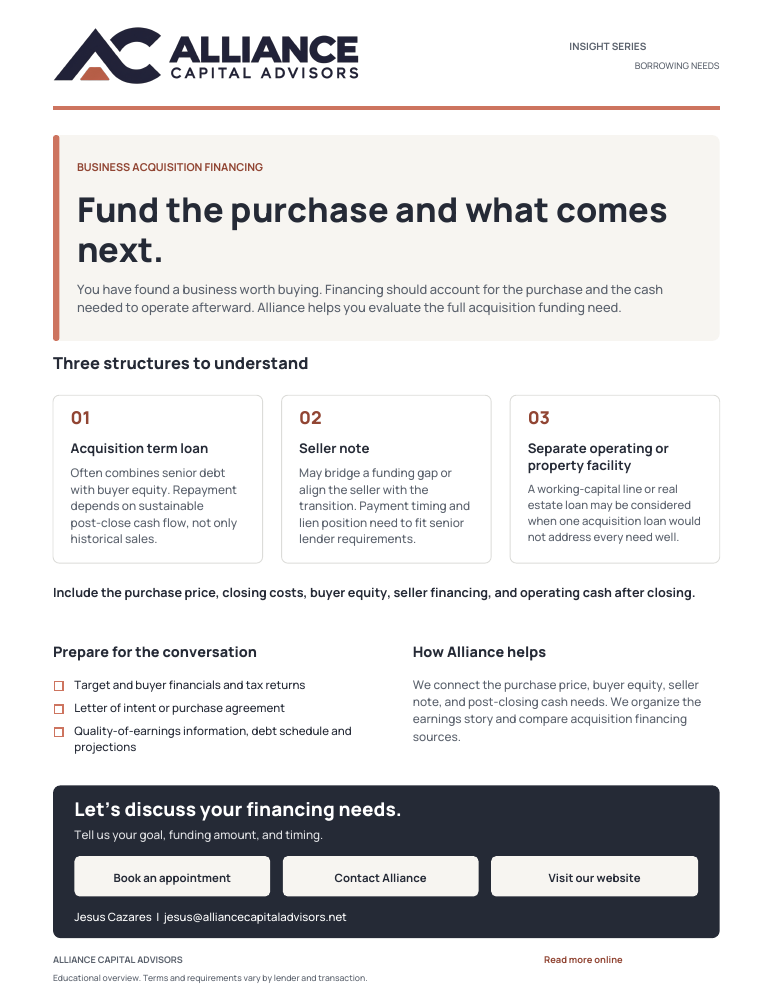
Explore this topic ↗You have found a business worth buying. Financing should account for the purchase and the cash needed to operate afterward. Alliance helps you evaluate the full acquisition funding need.
Explore this topic ↗An ownership change should leave the business prepared for its next chapter. Explore partner buyout and succession financing aligned with the company’s cash flow and ongoing needs.
Explore this topic ↗New contracts, locations, and customers bring opportunity, but expenses often arrive before revenue. Explore growth financing built around the cash your expansion needs.
Explore this topic ↗An approaching maturity or debt payments putting pressure on cash flow demand a clear plan. Explore refinancing and restructuring options aligned with your business or property goals.
Explore this topic ↗Your project needs financing aligned with its budget, schedule, and completion plan. Address construction funding requirements early so avoidable financing issues do not hold up the work.
Explore this topic ↗Financing Sources
Banks typically pair a financing request with a full review of cash flow, collateral, liquidity and the guarantor. Terms depend on the transaction and the lender.
Explore this topic ↗A government guarantee can help a participating lender support a transaction that needs a different risk structure. The lender still underwrites the request, and program rules change.
Explore this topic ↗Non-bank lenders may underwrite a transaction with a different view of collateral, cash flow, speed or a defined transition plan.
Explore this topic ↗These facilities put more weight on identified assets, contracts or receivables and how they convert to cash.
Explore this topic ↗How Financing Works
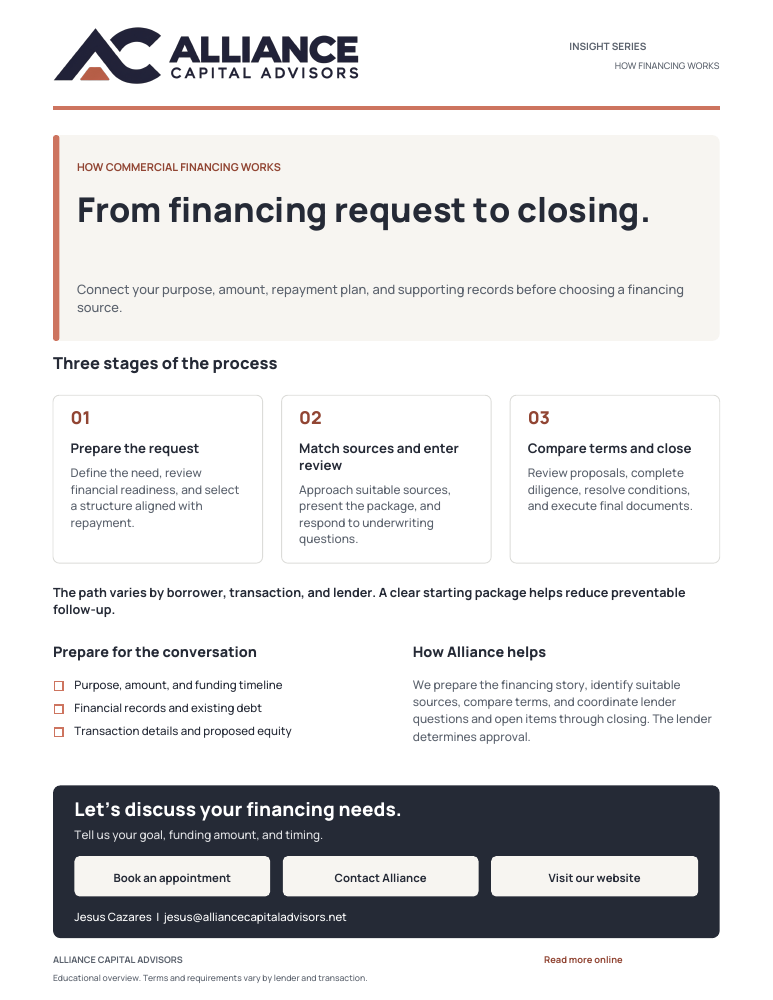
Connect your purpose, amount, repayment plan, and supporting records before choosing a financing source.
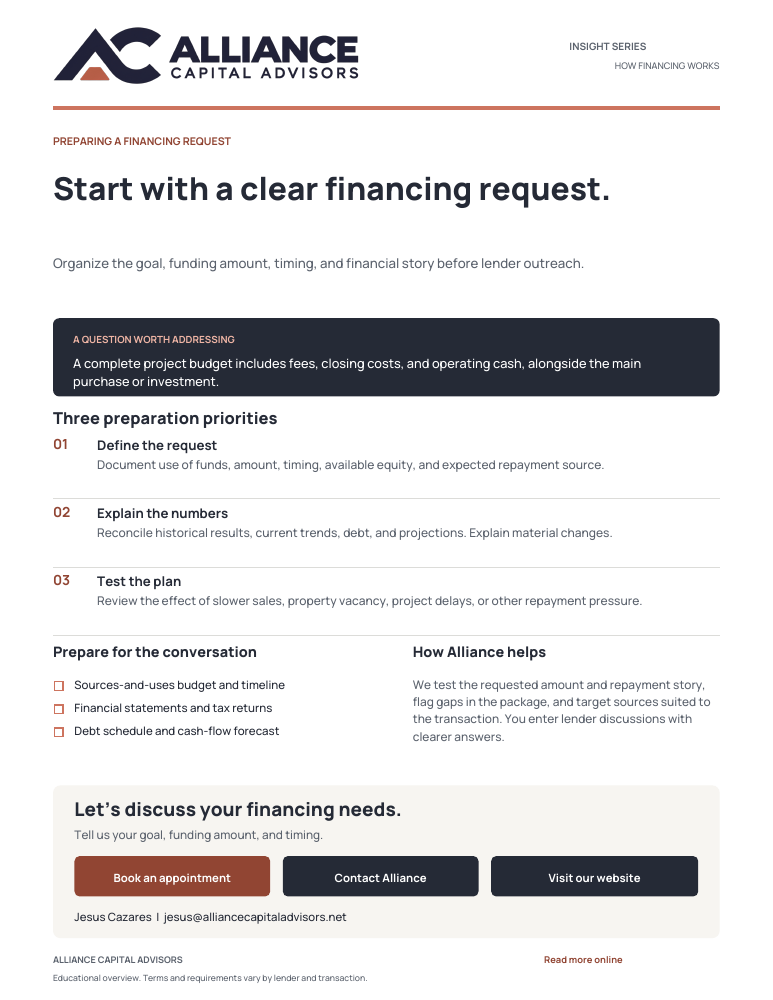
Explore this topic ↗Organize the goal, funding amount, timing, and financial story before lender outreach.
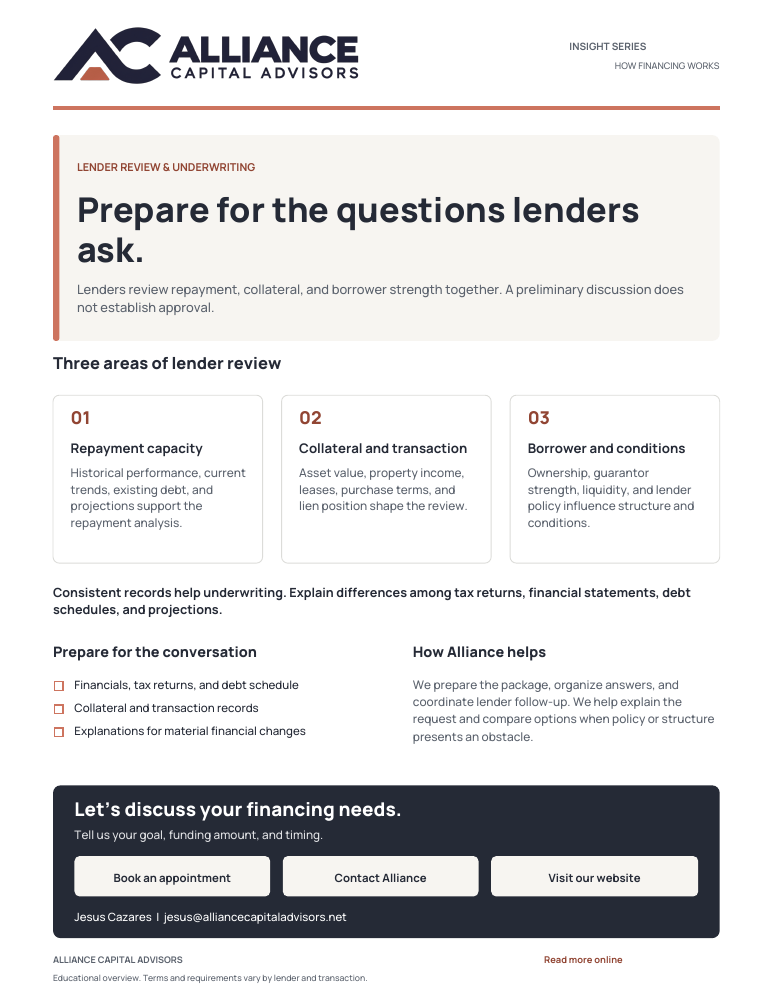
Explore this topic ↗Lenders review repayment, collateral, and borrower strength together. A preliminary discussion does not establish approval.
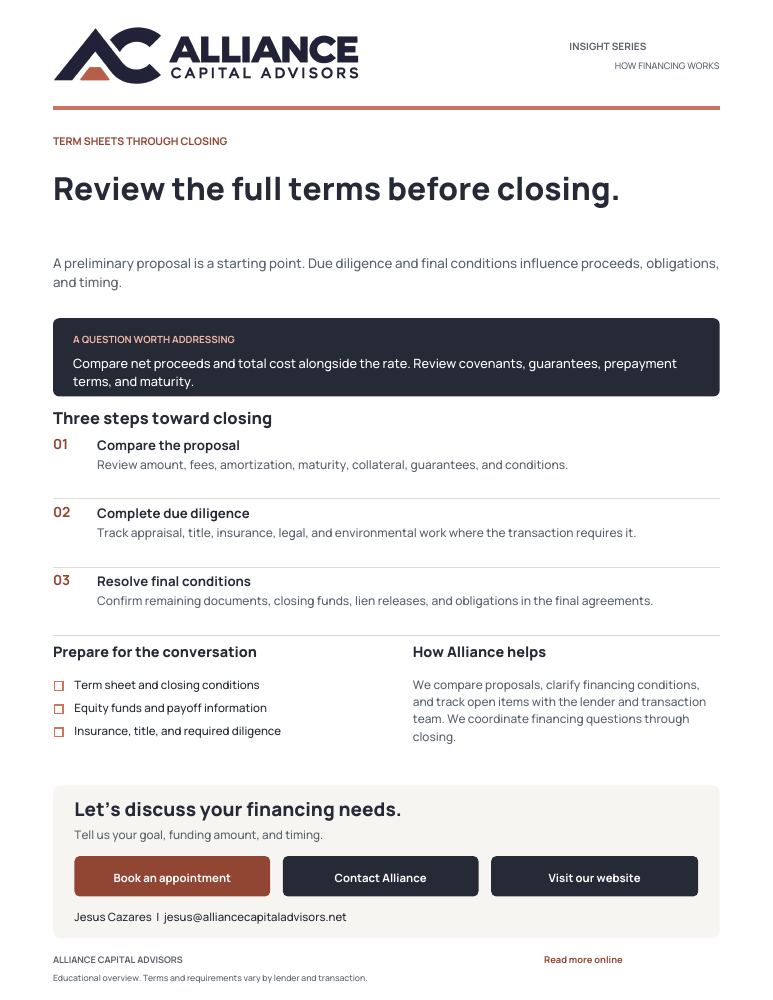
Explore this topic ↗A preliminary proposal is a starting point. Due diligence and final conditions influence proceeds, obligations, and timing.
Explore this topic ↗More Alliance resources
Services, financing preparation and commercial real estate checklists in English and Spanish.
Alliance services flyer
English PDF
Download PDF ↗Financing preparation guide
English PDF
Download PDF ↗Commercial real estate checklist
English PDF
Download PDF ↗Servicios de Alliance
PDF en español
Download PDF ↗Guía de preparación
PDF en español
Download PDF ↗Lista de bienes raíces comerciales
PDF en español
Download PDF ↗Build a clear financing request
Start with your goal, repayment story and documents. Then use the relevant property, acquisition or financial-measure guide to address likely questions before lender review.
Preparation and transaction checklists
Commercial Loan Documentation Checklist
A complete first package helps a lender understand the borrower, purpose, repayment and collateral together. Exact requirements vary, so start with core records and add transaction-specific support.
Read guide ↗Preparing for Commercial Financing
Preparation can protect time. Before outreach, align the business goal, requested amount, financial record and proposed source of repayment.
Read guide ↗Commercial Real Estate Financing Checklist
Property financing depends on both the real estate and the borrower. Organize property income, value, condition and transaction details before lender review.
Read guide ↗Preparing for an SBA Loan
SBA programs are delivered through participating lenders and have different permitted uses and requirements. Confirm current SBA and lender rules before selecting a path.
Read guide ↗Business Acquisition Financing Guide
Acquisition funding must cover more than the purchase price. The buyer needs a supportable repayment plan and enough liquidity to operate after closing.
Read guide ↗Understand the numbers and loan terms
Understanding DSCR
Debt service coverage ratio compares measured cash available for debt payments with required debt service. For example, $125,000 of available cash divided by $100,000 of annual payments is 1.25x. Lender definitions and required levels vary.
Read guide ↗Understanding Global Cash Flow
Global cash flow looks beyond one borrowing entity when related owners and businesses may affect repayment. It brings income, distributions, obligations and guarantees into one view.
Read guide ↗Understanding Loan-to-Value
Loan-to-value divides a loan amount by the accepted value of its collateral. A $1.5 million loan on a $2.5 million property value is 60% LTV. A lender may use a different lending value or include other secured debt.
Read guide ↗Understanding Debt Yield
Debt yield is annual property net operating income divided by loan amount. For example, $150,000 NOI divided by a $1.5 million loan is 10%. It is one way to view property leverage, alongside DSCR and LTV.
Read guide ↗Understanding Loan Covenants
Loan covenants are obligations in financing documents. They may require reports, minimum coverage or liquidity, and limits on additional debt or distributions. Details are transaction specific.
Read guide ↗Understanding Commercial Loan Term Sheets
A term sheet outlines the proposed financing, often subject to underwriting and documentation. Compare the whole structure before relying on a headline rate or maximum loan amount.
Read guide ↗Turn preparation into a financing plan
Preparation should give you direction, not another pile of tasks. Alliance connects these questions to your business or property, identifies the issues most likely to affect lender review, and targets suitable sources. You gain a clearer next step and spend less time guessing. Lender and program requirements vary.
LET’S TALK
Your next step starts with a conversation.
Tell us what’s holding up your financing and what you want to accomplish. We’ll discuss your options and how Alliance would help you move forward.